Why do investors continue to pay attention to real assets, especially when public markets, housing costs, and capital markets remain unsettled? Real assets remain relevant because they give investors a more concrete basis for evaluation. Instead of relying only on daily price movement or public-market sentiment, investors can look at the property, operating business, cash flow, and real economic demand behind the opportunity. The risks still need to be understood clearly, but the review starts from identifiable assets and operating activity. That visibility is a major part of the appeal. Investors can assess how the asset is expected to produce value, what supports the cash flow, and how the investment fits within a broader portfolio. The discussion moves beyond broad asset-class labels and into the mechanics of ownership. In a market where sentiment can shift quickly, a clearer view of the underlying asset gives investors a stronger basis for evaluating its role in a long-term strategy. Grounded in the real economy Public markets can move quickly based on interest-rate expectations, policy headlines, earnings revisions, and investor sentiment. Real assets invite a different kind of analysis. Investors look at the property, the business activity around it, the cash flow it can support, and the demand behind the asset. Housing is a useful example. The Harvard Joint Center for Housing Studies’ 2026 report found that persistent affordability challenges, rising economic uncertainty, and softer construction activity continue to pressure U.S. housing conditions. At the same time, NAR reported that existing-home sales decreased 2.4% month over month in June 2026, while total housing inventory stood at 1.56 million units. For investors, those conditions point to a market that still requires discipline. Real assets can offer exposure to long-term demand, but outcomes depend on price, execution, financing, and the ability to manage changing conditions. A Clearer View of Ownership Real assets can make the investment review more concrete because value is tied to identifiable sources. Investors can look at the location of a property, the demand behind a business, the terms of a loan, or the cash flow supporting the strategy. Those details help move the analysis beyond broad market exposure and toward a clearer understanding of how value is expected to be created over time. This is especially important when borrowing costs remain elevated. Freddie Mac reported that the 30-year fixed-rate mortgage averaged 6.58% as of July 23, 2026. Higher rates affect buyers, sellers, borrowers, and operators. They also put more pressure on the quality of underwriting and the discipline behind each investment decision. Real-asset investing works best when investors understand how the asset creates value, produces cash flow, and fits within the broader portfolio. Visibility gives investors a stronger foundation for evaluating risk. How Fund II fits the strategy Wingfield Financial evaluates real-asset exposure by the role it plays in the investment strategy and how clearly the underlying asset or business supports long-term value creation. Clarity becomes especially important for investors looking beyond public-market exposure. Real assets can play a useful role in a long-term portfolio when the investment case is grounded in identifiable assets, cash flow, risk management, and a defined hold period. The strongest real-asset review stays practical. It connects tangible exposure with how value is created, how risks are managed, and how the investment fits within broader long-term capital goals. Wingfield Financial Fund II is currently open to accredited investors. Learn more and get in touch. Sources: 1. Harvard Joint Center for Housing Studies: State of the Nation’s Housing 2026 Press Release 2. NAR: Existing-Home Sales Report Shows 2.4% Decrease in June 3. Freddie Mac: Mortgage Rates and Affordability 4. BlackRock: 2026 Private Markets Outlook for U.S. Wealth
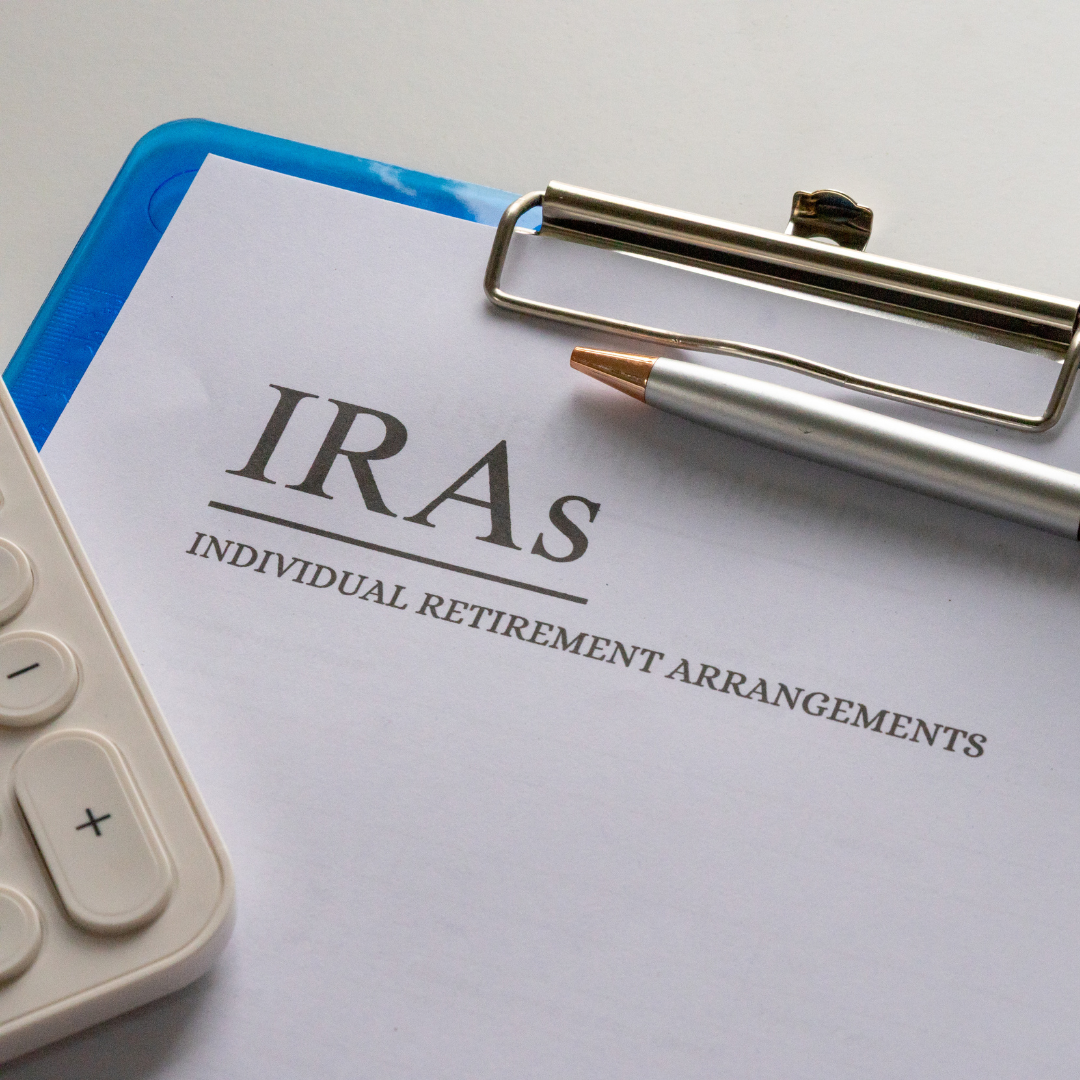
A look at self-directed IRAs, alternative investments, and what accredited investors should understand before using retirement capital in a private fund. Most investors think about retirement capital through the same familiar categories: stocks, bonds, mutual funds, and publicly traded accounts. Those tools remain important, but they are no longer the only ones sophisticated investors are having conversations about. For qualified investors, a self-directed IRA can create access to alternative assets that sit outside traditional public-market exposure. The FINRA, SEC, and NASAA investor alert on self-directed IRAs notes that custodians for these accounts may allow investments in assets such as real estate, private placement securities, promissory notes, and other alternatives. Self-directed retirement investing gives qualified investors another way to think about long-term capital beyond the public markets. The opportunity lies in putting long-term capital to work with more purpose. What a self-directed IRA can do A self-directed IRA allows qualified investors to hold certain alternative assets in a retirement account, provided the investment complies with IRS rules and the account is administered through the appropriate custodian. For investors who already understand private funds, real estate, or alternative strategies, this can open a more strategic conversation about how retirement capital is allocated. As alternative investments become a larger part of the market, qualified investors are looking more closely at how long-term capital can move beyond public-market exposure. Preqin forecasts global alternatives markets to exceed $30 trillion by 2030 , while BlackRock’s 2026 Private Markets Outlook for U.S. Wealth says private markets are moving from niche allocations toward more important roles in resilient portfolios. Accredited investors should focus on fit: whether the asset, account structure, timeline, and risk profile support the purpose of the retirement capital. The rules matter Self-directed doesn’t mean unrestricted. In fact, the IRS guidance on prohibited transactions explains that improper use of an IRA by the owner, beneficiary, or a disqualified person can create serious tax consequences. Investors should approach self-directed IRA investing as both a planning decision and an investment decision. The custodian, documentation, use of funds, liquidity profile, and tax considerations all matter. Retirement capital usually carries a longer time horizon, which can fit certain private investment strategies, but investors still need to understand how long capital may be committed and what rules govern the account. A self-directed IRA can be powerful when used correctly. It requires discipline, documentation, and a clear understanding of what the capital is meant to do. What this means for Fund II investors Many conversations around self-directed retirement capital begin with purpose. An investor should understand what role the capital is meant to play, how long it can remain invested, and what kind of exposure makes sense beyond public markets. A private investment may be available through a self-directed IRA, but availability alone is not enough. The investment still has to fit the account’s timeline, rules, liquidity needs, and broader retirement strategy. From there, the assessment becomes more practical. Retirement capital is often long-term by nature, which can make it well suited to certain private investment strategies. At the same time, investors still need to review the documentation, understand the risks, and make sure the account is being used properly. The value comes from aligning private investment access with the purpose of the account, so the capital is not only invested differently, but deployed with a clearer long-term objective. Wingfield Financial Fund II is currently open to accredited investors. Learn more and get in touch. Sources: 1. FINRA: Self-Directed IRAs and the Risk of Fraud 2. IRS: Retirement Topics - Prohibited Transactions 3. Preqin: Global Alternatives Markets on Course to Exceed $30tn by 2030 4. BlackRock: 2026 Private Markets Outlook for U.S. Wealth
The investor experience is shaped after the commitment is made. Here’s what accredited investors should look for. Most private fund conversations focus on what happens before capital is committed: the opportunity, the projected return, the structure, and the timeline. Those details matter, but they only tell part of the story. The more revealing question is what happens after the investment is made. Once capital is deployed, investors begin to see how the firm actually operates: how updates are delivered, how documents are organized, and how responsive leadership remains after the initial conversation ends. In a private fund with a multi-year hold, those details are part of the investment experience, not administrative follow-up. That matters because private investments are generally less liquid than public securities. The SEC’s investor bulletin on Regulation D private placements notes that these offerings can involve limited liquidity and different disclosure requirements than registered public offerings. Investors need to understand the relationship they are entering, not only the opportunity they are evaluating. Communication Should Be Built Into the Process Investors should understand how communication works before the first distribution is ever discussed. How often will updates be provided? Where will documents be stored? Who responds to investor questions? What information is included in reporting? How does the manager communicate if something changes? The answers reveal how seriously a firm treats stewardship. Even when a fund is built around strong assets, inconsistent communication can make the investor experience feel unclear. A well-run process gives investors a clearer view of how capital is managed and how the strategy progresses over time. This is also why private markets have placed more emphasis on reporting standards. The Institutional Limited Partners Association’s reporting template was designed to encourage transparency and alignment between limited partners and general partners. For individual accredited investors, the same principle applies. Clear reporting helps investors stay connected to the fund experience throughout the hold period. Longer Holds Require Better Communication Private fund investing usually requires patience. Investors may commit capital for several years, and they may not have the same ability to exit quickly if their circumstances change. That makes communication more important over time, especially when market conditions shift or timelines extend. Liquidity timing has also become a larger issue across parts of the private markets. McKinsey’s 2026 Global Private Markets Report found that private equity distributions as a share of assets under management were about 6% in the 12 months ending June 2025, compared with a 2015–2019 average of 16%. That does not mean private investing has lost its value. It means investors need a clear view of what is happening while their capital is committed. Regular updates help create that visibility. Investors should know where documents live, when to expect communication, and how questions will be handled. Over the course of a multi-year investment relationship, those details can make the difference between feeling informed and feeling disconnected from the fund. Trust is built through consistency. A clear update, an accessible document, a direct answer, and a steady communication rhythm all matter more as the hold period lengthens. Wingfield Financial Fund II is currently open to accredited investors. Learn more and get in touch. Sources SEC’s investor bulletin on Regulation D Institutional Limited Partners Association McKinsey’s 2026 Global Private Markets Report
A breakdown of what preferred returns actually mean, why structure matters, and what accredited investors should look for before committing capital to a private fund. Most investors start with the return. They’re simple to compare, easy to remember, and useful in a first conversation. A stated preferred return can make a private fund feel more concrete. Experienced investors, on the other hand, move quickly to a better question: how is the return structured? A preferred return gives investors a priority position in the distribution waterfall. This means that investors are scheduled to receive a stated return before the sponsor or manager participates in certain upside economics, subject to the fund documents. Think of it as a structure, not a guarantee. That distinction matters as more capital moves into private markets. Preqin projects global alternatives assets under management to reach $29.2 trillion by 2029 , up from $16.8 trillion at the end of 2023. As the category grows, investors need to look beyond headline targets and understand how private funds manage cash flow, risk, and alignment. What a preferred return is designed to do A preferred return is one way a fund sets expectations before performance becomes a success story. It gives investors a clearer view of how distributions are intended to move through the fund: first toward returning capital and meeting the preferred return, then toward any additional economics available to the sponsor. For accredited investors, this matters because the structure shows whether the fund is built around investor priority from the beginning, or whether the return is simply being used as a headline. That priority can also shape how a manager operates. Before the upside story matters, the fund has to be managed with attention to deployment, reserves, timing, cash flow, and downside protection. For investors, that discipline can be more meaningful than the preferred return number on its own. Preferred does not mean automatic A preferred return gives investors a clearer framework for how distributions are intended to work. Rather than removing the normal risks of private investing or guaranteeing a specific outcome, it establishes a priority in the fund documents around how available cash flow is distributed. For accredited investors, that structure can make the economics easier to evaluate and the manager’s alignment easier to understand. Investors still need to understand the business model, timeline, use of proceeds, manager’s track record, and risks tied to the strategy. The SEC’s guidance on Regulation D private placements notes that these offerings can involve limited liquidity and different disclosure requirements than public investments, making due diligence especially important. Why structure matters now Private investments usually require patience. Capital is often committed for a defined hold period, and investors cannot always exit quickly. That is especially relevant today. McKinsey’s 2026 Global Private Markets Report finds that distributions as a share of assets under management fell to about 6% in the six months ending June 2025, well below the 2015–2024 average of 14%. In plain English: liquidity timing matters. Returns will always matter, but they should be evaluated alongside the structure built to support them. A preferred return can give investors a useful starting point, but the deeper diligence is in how the fund manages investor priority, sponsor incentives, cash flow, timing, and downside protection. Accredited investors should look beyond the headline return and assess the discipline behind it, from investor priority and cash flow timing to sponsor alignment and downside protection. Wingfield Financial Fund II is currently open to accredited investors. Learn more and get in touch. Sources Global alternatives markets on course to exceed $30tn by 2030 — Preqin forecasts Private Placements under Regulation D – Updated Investor Bulletin Private equity: Clearer view, tougher terrain

Due diligence questions every accredited investor should ask before committing capital to a private equity fund.
Unique private equity offering builds on proof of concept with vertically integrated real estate, lending, construction, and business equity model. Wingfield Financial has launched Wingfield Financial Fund II, a $25 million private equity offering for verified accredited investors seeking access to operator-led, asset-backed investment opportunities across real estate, lending, construction, title, and business equity. Fund II builds on Wingfield Financial's first fund, a $1 million offering launched in 2022 that began investor distributions in January 2023. The fund's distribution structure is designed around preferred returns of 15 percent annually, though past performance is not indicative of future results, and Fund II is a separate, larger vehicle with different scale, market exposure, and execution considerations. It's built around a vertically integrated platform comprising four affiliated operating companies: Momentum Mortgage, Radical Restoration, Solution Providers, and Legacy Title. Together, they support acquisition financing, construction and property work, deal sourcing, and transaction closings within a single ecosystem. "Most funds this size call a lender, call a contractor, and call a title company," says John R. Clark, Jr., Principal and Founder of Wingfield Financial. "We built and own that infrastructure ourselves. That gives us greater involvement across execution, timing, reporting, and investor communication." The structure is designed to address common private investment concerns, including third-party coordination, limited transparency, concentration risk, and passive capital deployment. Fund II expects to allocate capital across sectors including mortgage, real estate, technology, title, insurance, construction, and distribution. Curt Anderson, a Fund I investor who subsequently reinvests in Fund II, cites the platform's operating model as a key factor in his decision. Anderson, a government contractor and real estate investor, first subscribed to Fund I through a self-directed IRA in early 2023 after conducting independent due diligence. Fund II is structured under Regulation D 506(c) and is available only to verified accredited investors. The offering includes a $100,000 minimum investment, a 36-month minimum hold, a callable option after 48 months, self-directed IRA eligibility through Equity Trust, and investor reporting through an Agora portal. About Wingfield Financial Wingfield Financial is an operator-led private equity platform focused on asset-backed investment opportunities across real estate, lending, construction, title, business equity, and related sectors. The firm is built around a vertically integrated operating model that connects capital deployment with direct execution through affiliated companies, including Momentum Mortgage, Radical Restoration, Solution Providers, and Legacy Title. Led by Principal Partner John R. Clark, Jr., Wingfield Financial brings more than 30 years of real estate and financial services experience to a platform focused on investor alignment, operational involvement, and long-term value creation. Accredited investors interested in learning more may contact John R. Clark, Jr. at jclark@wingfieldfinancial.com or visit wingfieldfinancial.com. Disclaimer This press release is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy securities. Any offering will be made only pursuant to official offering documents and in accordance with applicable securities laws. Fund II is available only to verified accredited investors. Past performance is not indicative of future results. Investment involves risk, including the possible loss of principal. Also featured on AP News , Investor News Update , and T he Capitol Report er

What separates operator-led private equity from traditional PE? Wingfield Financial breaks down the structural difference and what it means for investor returns.
Stock market volatility in 2026 is pushing accredited investors toward alternatives. Here is why operator-led private funds are drawing serious attention right now.